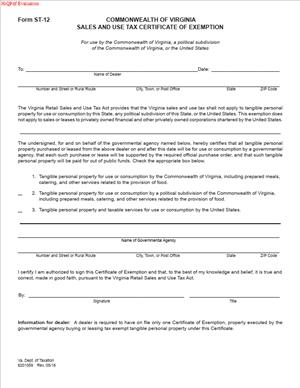
Form ST-12 – Sales And Use Tax Certificate of Exemption
Fill out nowJurisdiction: Country: United States | Province or State: Virginia
Form ST-12 – Sales And Use Tax Certificate of Exemption is a document used in Virginia to claim an exemption from sales and use tax on certain purchases. If you are about to present or complete this form, you are likely trying to buy items without paying Virginia sales tax at the point of sale.
This form is commonly used by businesses, nonprofit organizations, and other qualifying entities. It allows the seller to document why tax was not collected on a transaction. Without a properly completed certificate, most sellers are required to charge sales tax.
You may encounter this form when purchasing items for resale, for use in manufacturing, or for other qualifying exempt purposes. It acts as proof that the transaction meets an exemption category recognized by the Commonwealth of Virginia – Department of Taxation.
Filling out this document correctly matters. An incomplete or inaccurate form can lead to tax being charged, delayed transactions, or future tax assessments. Understanding what the form does—and what it does not do—helps you avoid problems later.
What is Form ST-12 – Sales And Use Tax Certificate of Exemption?
Clear definition
Form ST-12 – Sales And Use Tax Certificate of Exemption is a written certification provided by a purchaser to a seller. In it, the purchaser states that the items being bought qualify for a specific sales and use tax exemption under Virginia law.
The document identifies the purchaser, describes the nature of their business or activity, and states the legal basis for the exemption. By signing it, the purchaser affirms that the information is true and that the purchase meets the stated exemption category.
The seller keeps the completed form in their records. This documentation supports the seller’s decision not to collect sales tax on the transaction.
Who typically uses this form?
Businesses that resell goods often use this form. For example, a retail store purchasing inventory for resale may provide this certificate to its supplier.
Manufacturers may also use it when buying machinery, tools, or materials that qualify for manufacturing exemptions. Contractors and service providers may encounter it in limited circumstances tied to specific statutory exemptions.
Certain nonprofit entities and other qualifying organizations may use similar exemption certificates. However, not all nonprofits qualify under the same rules, and the eligibility depends on the type of exemption claimed.
In most cases, the person completing the form is an owner, officer, or authorized representative of the purchasing business or organization.
Why might you need this form?
You need this form when you want to purchase tangible personal property without paying Virginia sales tax, and you qualify for an exemption category recognized by law.
Without a valid exemption certificate, the seller is generally required to collect tax. Even if you believe the purchase is exempt, the seller may not accept your claim unless you provide proper documentation.
This form also protects the seller. If the transaction is later reviewed, the seller can show that they relied on a completed exemption certificate provided by the buyer.
For you, as the purchaser, the form helps establish a record of why tax was not paid at the time of purchase. That record can become important if your purchases are ever examined.
Typical real-life scenarios
- You operate a clothing boutique in Virginia. You purchase shirts and accessories from a wholesaler to resell in your store. Because you will collect sales tax from your customers at the retail level, you provide an exemption certificate to the wholesaler so you are not taxed twice.
- You run a manufacturing facility that produces custom metal parts. You buy raw materials that will become part of the finished product. You provide the certificate to claim the exemption that may apply to materials used directly in manufacturing.
- You purchase packaging materials that will be transferred to customers along with the goods you sell. In some situations, these materials may qualify for exemption, and you use the form to document that claim.
- You manage a business that regularly orders equipment and supplies from out-of-state vendors. When those vendors ship items into Virginia, you may need to document why certain purchases qualify for exemption under Virginia rules.
- In each of these situations, the form is not a blanket permission to avoid tax. It applies only to qualifying purchases that fit within the exemption category you certify.
When would you use Form ST-12 – Sales And Use Tax Certificate of Exemption?
You use this form at the time of purchase or before the seller finalizes the transaction. It is typically provided to the seller before tax is charged.
Many sellers request the certificate during account setup. If you open a business account with a supplier and intend to make tax-exempt purchases, the seller may ask you to complete the form once and keep it on file.
You may also use it for individual transactions. For example, if you normally pay tax but have a specific purchase that qualifies for exemption, the seller may require a completed certificate for that transaction only.
Purchasers who operate in multiple states often manage different exemption certificates for each state. This form is specific to Virginia. If your business buys goods for use in Virginia, this is the certificate generally used to document exemption claims in this jurisdiction.
Roles that commonly interact with this document include business owners, purchasing managers, accountants, and accounts payable staff. On the seller’s side, sales staff and compliance teams review and retain the completed forms.
Timing matters. If you do not provide the certificate until after tax has been charged and paid, correcting the transaction may require additional steps beyond simply handing over the form.
Legal characteristics of Form ST-12 – Sales and Use Tax Certificate of Exemption
This document functions as a certification under penalty of law. By signing it, you attest that the purchase qualifies for the exemption selected and that the information provided is accurate.
For the certificate to be effective, it typically must be fully completed. Missing information, such as a registration number or description of the business, can cause the seller to reject it. An unsigned form is generally not valid.
The form must clearly state the exemption category being claimed. If the exemption box is not selected or is inconsistent with the purchaser’s business activity, the seller may question its validity.
Sellers are not required to accept a certificate that appears improper on its face. If the claimed exemption does not reasonably match the nature of the buyer’s business, the seller may choose to collect tax instead.
Different states have their own exemption forms and standards. A certificate from another state is not automatically valid for Virginia transactions. Likewise, this certificate is designed for use under Virginia law.
It is important to understand what the document does not do. It does not create an exemption where none exists. It does not replace a required tax registration. It does not eliminate your obligation to pay use tax if an exemption does not actually apply.
If an exemption is later found to be invalid, responsibility for unpaid tax may shift. In many situations, the purchaser who provided the certificate may be held liable for tax, interest, and possibly penalties.
Is it legally binding?
Yes, in practical terms, this certificate carries legal significance. When you sign it, you are making a formal representation that your purchase qualifies for exemption under Virginia sales and use tax law.
The seller relies on your certification when deciding not to collect tax. That reliance can protect the seller during a review or audit, provided the certificate was accepted in good faith and appears complete and reasonable.
For you as the purchaser, signing the certificate creates accountability. If the information is incorrect or if the purchase does not actually qualify, you may be responsible for the tax that was not paid at the time of sale.
The certificate is binding in the sense that it documents your statement of fact. It is not a contract between buyer and seller in the traditional sense, but it is a formal tax document with consequences tied to its accuracy.
How to fill out Form ST-12 – Sales and Use Tax Certificate of Exemption
Step 1 – Enter the purchaser’s legal name and business information
Begin by writing the full legal name of the business or organization claiming the exemption. Use the name as it appears on official registrations and tax records.
Include the business address, city, state, and ZIP code. This identifies who is making the certification and where the business operates. Make sure the address is current and complete.
Step 2 – Provide your Virginia tax registration number
Enter the Virginia sales and use tax registration number, if required on the form. This number connects your business to its tax account with the state.
Double-check the number for accuracy. An incorrect registration number can cause the seller to question or reject the certificate. If you are not registered, the form may not be appropriate for your situation.
Step 3 – Describe the nature of your business
The form typically asks for a brief description of your business activity. Provide a clear and specific description, such as retail clothing sales, commercial printing, or metal fabrication.
Avoid vague terms. The description should reasonably match the exemption category you plan to select. This helps the seller determine whether the claim appears consistent.
Step 4 – Select the appropriate exemption category
Review the exemption options listed on the form. These categories correspond to specific statutory exemptions, such as resale, manufacturing, or other qualifying uses.
Mark the box that applies to your purchase. Only select the category that accurately reflects how the items will be used. The exemption you choose should align with both your business activity and the items being purchased.
Take time to ensure that the category fits the transaction. Selecting the wrong exemption can create issues later.
Step 5 – Confirm the intended use of the property
Some versions of the form require you to state that the tangible personal property will be used in a particular way. Read this section carefully before signing.
By completing this part, you confirm that the items purchased will be used solely for the exempt purpose described. If the items are later used for a taxable purpose, additional tax obligations may arise.
Make sure your internal purchasing practices match the certification you are making on the form.
Step 6 – Sign and date the certificate
An authorized individual must sign the form. This is often an owner, corporate officer, or another person with authority to bind the business in tax matters.
Print your name and title clearly. Then enter the date of signing. The signature confirms that the information provided is accurate to the best of your knowledge.
Do not leave the signature line blank. An unsigned certificate is generally not valid.
Step 7 – Provide the completed form to the seller and retain a copy
Once completed, deliver the certificate to the seller before or at the time of purchase. The seller will typically keep the original for their records.
Keep a copy for your own files. Maintaining organized records helps you track which vendors have exemption certificates on file and which exemption categories you have claimed.
Store the document with your tax and accounting records so it is available if questions arise about past transactions.
Legal terms you might encounter in Form ST-12 – Sales And Use Tax Certificate of Exemption
- Purchaser: This is you or your business when you are buying goods and claiming an exemption from sales tax. On this form, the purchaser is the party completing and signing the certificate. The name you enter must match your legal business name or registered individual name.
- Dealer: The dealer is the seller who would normally collect sales tax on the transaction. You give the completed certificate to the dealer so they can justify not charging you sales tax. The dealer keeps it in their records.
- Sales and Use Tax: Sales tax applies to taxable items sold at retail. Use tax applies when taxable items are purchased without sales tax and then used in the state. This certificate allows you to claim that a specific purchase is exempt from those taxes under state law.
- Exemption Category: This refers to the legal reason your purchase qualifies for tax-free treatment. The form lists specific categories, such as resale, manufacturing, nonprofit use, or government purchases. You must select the category that accurately matches how you will use the property.
- Virginia Tax Registration Number: This is the identification number assigned to your business for state tax purposes. You enter it to show that you are registered with the state for tax reporting. Dealers rely on this number to validate your exemption claim.
- Tangible Personal Property: This means physical items you can see and touch, such as equipment, supplies, or inventory. The certificate applies to qualifying purchases of tangible personal property. It does not automatically cover services unless specifically allowed by law.
- Good Faith Acceptance: This concept protects the seller if they accept your certificate without knowing it is incorrect. The dealer must accept the certificate in good faith, meaning they reasonably believe your exemption claim is valid. If your claim is false, you—not the dealer—may be responsible for unpaid tax.
- Misuse of Exemption Certificate: This occurs when someone claims an exemption for items that do not qualify. Misuse can lead to tax assessments, penalties, and interest. When you sign the form, you are certifying that the information is true and that the items will be used as described.
- Authorized Signature: The person signing must have authority to bind the purchaser. For a business, this is usually an owner, officer, or authorized employee. The signature confirms that the statements on the certificate are accurate and complete.
FAQs
Do I send Form ST-12 – Sales And Use Tax Certificate of Exemption to the state tax department?
No. You generally provide this document directly to the seller, not to the tax agency. The seller keeps it in their records to show why they did not charge you sales tax. You should also keep a copy in your own files in case of an audit.
What information must match my official tax registration records?
Your legal business name and tax registration number must match what appears in your state tax account. If the name on this form is slightly different from your registered name, the seller may reject it. Always confirm the exact spelling and number before you submit the certificate.
Can I use this document for multiple purchases?
In many cases, you can provide a blanket certificate that covers ongoing purchases of qualifying items. However, it only applies to items that fit the exemption category you selected. If your use changes, you may need to provide a new certificate.
What if I do not have a Virginia tax registration number yet?
If you are required to have one for the exemption you are claiming, you should obtain it before completing this form. Leaving the registration number blank can cause the seller to refuse the exemption. Some exemption categories may have different documentation requirements, so confirm what applies to your situation.
Who is allowed to sign this form?
An owner, corporate officer, partner, or other authorized employee may sign, as long as they have the authority to bind the business. The signature certifies that the items purchased qualify for exemption. If you are an individual purchaser, you sign in your own name.
Does this certificate have an effective date?
The effective date is generally the date you sign it and give it to the seller. It does not usually apply retroactively to past purchases unless the seller agrees and keeps it on file for those transactions. Always check the date you enter to ensure it matches when the exemption should begin.
What happens if I use the exemption for items that do not qualify?
If you misuse the certificate, you may owe the unpaid sales or use tax, plus interest and possible penalties. The seller may rely on your signed statement, so the responsibility shifts to you. Review the exemption category carefully before claiming tax-free status.
Do I need to attach supporting documents when I submit this form?
Most sellers only require the completed and signed certificate. However, they may request proof of your tax registration number or documentation showing your business type. Be prepared to provide additional information if the seller asks for verification.
Checklist: Before, During, and After Form ST-12 – Sales And Use Tax Certificate of Exemption
Before
- Confirm that your purchase qualifies under a specific exemption category.
- Verify your legal business name as registered with the state.
- Locate your Virginia tax registration number.
- Review how the purchased items will be used in your business.
- Make sure the person signing has authority to bind the business.
- Gather any supporting documents the seller might request.
- Check whether you need a single-use or blanket certificate.
- Ensure your business registration is active and in good standing.
During
- Enter your full legal name without abbreviations unless officially registered.
- Provide the correct and complete tax registration number.
- Accurately describe the nature of your business activities.
- Select the exemption category that matches the intended use.
- Double-check that the items purchased fit the exemption selected.
- Sign and date the certificate clearly.
- Print your name and title if signing on behalf of a business.
- Review the entire document for missing fields before submission.
After
- Give the completed certificate directly to the seller.
- Request confirmation that the seller has accepted it.
- Keep a signed copy in your tax records.
- Track which vendors have your certificate on file.
- Monitor purchases to ensure they stay within the exemption category.
- Update the certificate if your business name or registration number changes.
- Replace the certificate if your exemption status changes.
- Retain records in case of future tax review or audit.
Common mistakes to avoid with Form ST-12 – Sales And Use Tax Certificate of Exemption
- Mistake: Claiming an exemption without verifying eligibility, often because the category sounds similar to your business activity, which can result in back taxes and penalties; do not forget to match the purchase to the exact exemption description.
- Mistake: Entering a trade name instead of the registered legal name, which happens when businesses operate under a different brand, leading to rejection by the seller; do not forget to use the name tied to your tax registration number.
- Mistake: Providing an incorrect or outdated tax registration number due to copying errors or old records, which may invalidate the certificate; do not forget to confirm the current number from official records.
- Mistake: Using one certificate for all purchases regardless of item type, often for convenience, which can trigger liability for non-qualifying items; do not forget that only certain purchases fit the selected exemption.
- Mistake: Allowing an unauthorized employee to sign, which can create internal disputes and questions about validity; do not forget to ensure the signer has formal authority.
- Mistake: Failing to keep a copy, usually because the seller retains the original, which leaves you unprepared during an audit; do not forget to store a complete copy in your tax files.
- Mistake: Not updating the certificate after a business name or ownership change, which can cause confusion and rejected exemptions; do not forget to issue a new certificate when key details change.
- Mistake: Assuming the exemption applies automatically to services, which often happens due to a misunderstanding of tax rules, leading to unpaid tax assessments; do not forget to confirm the exemption applies to tangible personal property as described.
What to do after filling out Form ST-12 – Sales and Use Tax Certificate of Exemption
Once you complete the form, your job is not finished. You need to manage how the certificate is delivered, stored, and monitored over time.
Start by reviewing the signed document one more time. Make sure the legal name, registration number, exemption category, and signature are clear and readable. Small errors can create larger tax issues later.
- Step 1: Make at least one copy of the signed certificate for your records, either paper or secure digital format.
- Step 2: Deliver the certificate directly to the seller before or at the time of purchase.
- Step 3: Ask the seller to confirm they have accepted it and applied the exemption to your account.
- Step 4: Check your invoice to ensure sales tax was not charged incorrectly.
- Step 5: Store your copy with your tax and accounting records.
- Step 6: Note which vendors have a certificate on file and the date you provided it.
- Step 7: Review your future purchases to confirm they fit the exemption claimed.
- Step 8: Update the certificate if your business information changes, such as name, structure, or tax registration number.
- Step 9: Replace the certificate if your business activities change and you no longer qualify under the selected category.
- Step 10: Keep the document accessible in case of audit or internal compliance review.
You should also coordinate with whoever handles your bookkeeping. Make sure they understand that certain purchases are tax-exempt and why. This prevents confusion when reconciling invoices or preparing tax returns.
Finally, treat this certificate as an active compliance document. It is not a one-time task. Review it periodically, especially if your operations expand into new product lines or services. Staying organized now reduces the risk of tax assessments, penalties, and unnecessary disputes later.
Disclaimer: This guide is provided for informational purposes only and is not intended as legal advice. You should consult a legal professional.