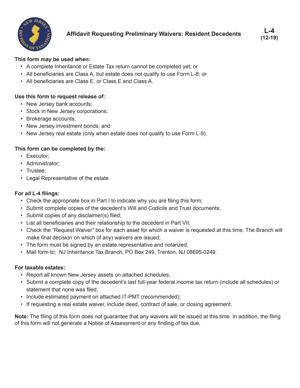
L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
Fill out nowJurisdiction: Country: United States | Province or State: New Jersey
If you are handling the estate of someone who lived in New Jersey and has passed away, you may come across the L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents. This document is used during the estate settlement process to help release certain assets.
The L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents is filed with the New Jersey Division of Taxation. It is part of the inheritance tax process. It allows specific assets to be transferred before the final tax clearance is issued.
You usually deal with this form when banks, brokerage firms, or other institutions will not release funds without proof that tax requirements are being addressed. The affidavit helps confirm that no inheritance tax is due for certain beneficiaries.
If you are serving as an executor, administrator, or beneficiary, understanding this form can save time and prevent delays. Knowing what it does—and what it does not do—makes the estate process clearer and more manageable.
What is L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents?
Clear definition
The L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents is a sworn statement used in New Jersey estates when the person who died was a resident of the state. It requests preliminary tax waivers for specific assets that pass to beneficiaries who are fully exempt from New Jersey inheritance tax.
A tax waiver is a written authorization from the state allowing a financial institution to release or transfer assets. Without it, institutions may freeze accounts belonging to the deceased person.
This affidavit tells the state that the assets in question are passing to exempt beneficiaries. Based on that information, the Division of Taxation may issue preliminary waivers so those assets can be accessed.
The form is not a general inheritance tax return. It applies in more limited situations where no tax is due because of the relationship between the decedent and the beneficiary.
Who typically uses this form?
Executors named in a will commonly complete this form. If there is no will, an administrator appointed by the court may use it.
In some cases, a surviving spouse or civil union partner involved in handling the estate may also take part in the submission. Attorneys often prepare the form, but individuals can complete it themselves if they understand the requirements.
The beneficiaries connected to this form are typically close family members. In New Jersey, transfers to certain relatives are generally exempt from inheritance tax. These relationships often include spouses, civil union partners, parents, grandparents, children, stepchildren, and grandchildren.
If the estate only includes beneficiaries in exempt categories, this affidavit becomes especially relevant.
Why might you need this form?
You may need this form because banks and other institutions often require a tax waiver before releasing funds held solely in the decedent’s name.
Even when no inheritance tax is owed, the institution may not release assets without proof from the state. The preliminary waiver serves as that proof.
Without filing this affidavit, you could face delays in accessing accounts needed to pay funeral expenses, debts, or ongoing estate costs.
The form also helps clarify to the state that the estate qualifies for exempt treatment, at least for the assets listed in the request.
Typical real-life scenarios
- A surviving spouse is the sole beneficiary under a will. The decedent had several bank accounts in his name only. The bank refuses to release the funds until it receives a tax waiver. The executor files the affidavit to obtain preliminary waivers so the accounts can be transferred.
- An adult child inherits her parents’ brokerage account. Because children are typically exempt from New Jersey inheritance tax, the executor uses this form to request a waiver for that account. This allows the brokerage firm to retitle or distribute the investments.
- A decedent leaves assets only to grandchildren. There are no other beneficiaries. The estate representative submits the affidavit to confirm that all transfers are to exempt beneficiaries and to request the necessary waivers for financial institutions.
- An estate includes a house and several financial accounts. The house passes to a spouse, and the accounts pass to children. Since all beneficiaries fall within exempt categories, the executor uses the form to obtain waivers for the accounts while continuing with other estate tasks.
When would you use L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents?
You use this form when the person who died was a New Jersey resident, and the assets in question are subject to inheritance tax procedures, but the beneficiaries are exempt from tax.
This usually happens early in estate administration. After the executor is appointed and begins gathering information about assets, financial institutions may request tax waivers before releasing funds.
If all beneficiaries listed for the relevant assets fall into exempt classes, this form may be appropriate. If some beneficiaries are not exempt, a different inheritance tax filing may be required.
You would not use this form for non-resident decedents. Different procedures generally apply when the deceased person lived outside New Jersey.
The form is also not used for assets that pass automatically outside the estate and do not require a tax waiver. For example, certain jointly held property or accounts with named beneficiaries may transfer without needing this document, depending on how they are structured.
Executors, administrators, and sometimes legal representatives typically handle the filing. The person completing the form must have knowledge of the estate and the relationships between the decedent and beneficiaries.
Timing matters. Filing too early, before confirming beneficiary details, can lead to corrections. Filing too late may delay access to estate funds.
Legal characteristics of L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
This document is an affidavit, which means it is a sworn statement. The person signing it declares that the information provided is true to the best of their knowledge.
Its effectiveness depends on accuracy and completeness. If beneficiary relationships are described incorrectly, or if assets are omitted or mischaracterized, the Division of Taxation may reject the submission or request additional information.
The form generally becomes effective once it is properly completed, signed, and accepted by the state. After review, the state may issue preliminary waivers for the listed assets.
Common reasons for problems include incomplete asset descriptions, missing signatures, or failing to identify the exact relationship between the decedent and each beneficiary. Inheritance tax classifications depend heavily on family relationships.
Another issue can arise if the estate actually includes beneficiaries who are not exempt. In that situation, a full inheritance tax return may be required instead of, or in addition to, this affidavit.
This document does not transfer property by itself. It does not replace probate, nor does it substitute for a will. It simply requests tax waivers so institutions can release specific assets.
Procedures and requirements may vary depending on whether the decedent was a resident or non-resident, and whether the estate includes taxable beneficiaries. The L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents is tailored to resident decedents with exempt beneficiaries.
Is it legally binding?
Yes, in the sense that it is a sworn affidavit. When you sign it, you are making a legal statement under oath. Providing false information can carry serious consequences.
It is binding as a declaration of fact. You are affirming the decedent’s residency, the identity of beneficiaries, and their relationship to the decedent.
However, the form itself does not create rights between beneficiaries. It does not determine who is entitled to inherit. That is controlled by the will or by intestacy law if there is no will.
Its legal force is limited to the tax waiver process. It authorizes the state to rely on your statements when deciding whether to issue preliminary waivers. Financial institutions rely on those waivers to release funds.
How to fill out L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
Step 1 – Review the decedent’s information
Start by gathering the basic details about the person who died. This usually includes full legal name, date of death, Social Security number, and last residential address. Confirm that the decedent was a resident of New Jersey at the time of death, since this form applies to resident decedents.
Make sure the information matches the death certificate and court documents. Inconsistencies can cause delays.
Step 2 – Confirm your authority
Identify your role in the estate. You may be the executor named in the will or the administrator appointed by the court. Have your appointment documents available, such as letters testamentary or letters of administration.
The form typically requires you to state your authority to act on behalf of the estate. Enter your name and contact information clearly.
Step 3 – Identify the beneficiaries
List each beneficiary who will receive the assets for which you are requesting preliminary waivers. Provide full legal names and addresses.
For each beneficiary, clearly state the relationship to the decedent. Be precise. For example, specify whether the person is a son, daughter, spouse, grandchild, or parent. The inheritance tax classification depends on this relationship.
Confirm that each listed beneficiary falls into an exempt category under New Jersey inheritance tax rules. The affidavit is based on that exemption.
Step 4 – Describe the assets
Identify the assets for which you are requesting waivers. These often include bank accounts, brokerage accounts, or other financial assets held solely in the decedent’s name.
Provide the name and address of each financial institution. Include account numbers or other identifying details as required on the form.
Describe the type of asset clearly. For example, indicate whether it is a checking account, savings account, certificate of deposit, or investment account. Accurate descriptions help the state issue correct waivers.
Step 5 – Confirm exempt status
The form typically includes statements affirming that the assets pass entirely to beneficiaries who are exempt from inheritance tax.
Read each statement carefully before signing. You are confirming that no part of the listed assets will pass to a non-exempt beneficiary.
If the estate includes both exempt and non-exempt beneficiaries, ensure that the assets listed on this form relate only to exempt transfers.
Step 6 – Review for completeness
Before signing, review every section. Check spelling of names, account numbers, and addresses. Confirm that all required fields are completed.
Make sure attachments, if any are required, are included. This may involve copies of appointment documents or supporting information.
Incomplete submissions are a common cause of delay.
Step 7 – Sign the affidavit
Because this is an affidavit, it must be signed under oath. Follow the signature instructions on the form carefully.
Sign your name exactly as printed in the identification section. Provide the date of signing. If notarization is required, ensure the document is properly notarized according to the form’s instructions.
Your signature confirms that the statements in the document are true to the best of your knowledge.
Step 8 – Submit the form
Prepare the form for submission to the appropriate state office. Confirm that you are sending the correct version and that all pages are included.
Keep a complete copy for your records. After submission, monitor for correspondence from the Division of Taxation in case additional information is requested.
Once preliminary waivers are issued, provide them to the relevant financial institutions so the assets can be released or transferred.
Legal terms you might encounter in L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
- Preliminary Waiver: A written authorization issued before final tax clearance that allows certain estate assets to be transferred. In this document, you request that authorization so banks or other institutions can release funds without waiting for a final tax determination. It does not mean all tax matters are finished. It simply allows limited transfers to move forward.
- Resident Decedent: A person who lived in the state at the time of death. This status determines which tax rules apply and which office processes your paperwork. You must confirm residency because this document is specifically for the estates of resident decedents.
- Executor: The individual named in a will and formally appointed to manage the estate. If you are the executor, you are responsible for completing and signing this affidavit. Your authority typically comes from official appointment papers.
- Administrator: A person appointed by a court to manage the estate when there is no valid will. If you serve in this role, you complete this form instead of an executor. Your authority must be supported by court-issued documentation.
- Beneficiary: A person or entity entitled to receive property from the estate. You must accurately list beneficiaries because the waiver affects how assets are released to them. Name accuracy matters. The information you enter becomes part of the official tax file.
- Transfer Inheritance Tax: A tax that may apply when property passes from a decedent to certain beneficiaries. The waiver process is connected to this tax because institutions often require confirmation that tax obligations are addressed before transferring assets. The affidavit helps move the process forward while the tax review continues.
- Tax Waiver: An official clearance document allowing the transfer of specific property. The affidavit is your request for this clearance. Without it, some financial institutions will freeze accounts.
- Affidavit: A written statement you sign under oath. By signing, you confirm that the information you provided is true and complete. False or incomplete statements can delay processing and create legal consequences.
- Estate Assets: Property owned by the decedent at death, including bank accounts, securities, and other financial holdings. You must describe these assets clearly so the waiver can be issued for the correct property. Vague descriptions often cause rejection.
- Letters Testamentary or Letters of Administration: Official court documents proving your authority to act for the estate. You may need to attach copies when requesting preliminary waivers. Institutions rely on these documents before releasing funds.
FAQs
Do I need to complete L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents before assets can be released?
Many financial institutions require a tax waiver before they will transfer or close a decedent’s account. This document is your formal request for that waiver. If the institution has frozen an account, ask them whether a preliminary waiver is required and confirm the exact account title that must appear on the form.
What information must exactly match other estate documents?
Names of the decedent and beneficiaries must match the death certificate and court appointment papers. Even small differences, such as missing middle initials, can delay processing. Check spelling, suffixes, and address details before you sign.
Who is allowed to sign this form?
Only the person with legal authority to act for the estate should sign. That usually means the executor named in court papers or the court-appointed administrator. Make sure your appointment documents are finalized and that you attach proof if required.
Do I need to attach supporting documents?
You may need to attach copies of appointment papers and sometimes a copy of the death certificate. Confirm that each attachment is clear and legible. If an attachment is missing, processing may stop until it is provided.
What happens after I submit this document?
The tax authority reviews the information you provided. If everything is complete, it may issue preliminary waivers for the listed assets. If information is unclear, you may receive a written request for clarification or additional documents.
Can I request waivers for multiple accounts at the same time?
Yes, but you must clearly identify each account, institution, and account number. If you leave out an account or describe it vaguely, that asset may not be covered. Review account statements to ensure you list them correctly.
Does this form mean the estate’s taxes are fully resolved?
No. A preliminary waiver allows certain transfers before the final tax review is complete. You may still need to file additional tax returns or provide further information later.
What if I realize I made an error after submitting this document?
Act quickly. Prepare a corrected version or written explanation and follow the submission instructions used for the original filing. Clearly reference the decedent’s name and date of death so the correction is matched to the right file.
Checklist: Before, During, and After L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
Before
- Obtain certified copies of the death certificate.
- Secure official court appointment documents proving your authority.
- Gather recent statements for all estate bank and financial accounts.
- Confirm the decedent’s legal name and last address.
- Verify the full legal names and addresses of beneficiaries.
- Review whether any transfer inheritance tax filing is required.
- Make a list of each asset for which you need a preliminary waiver.
- Confirm institutional requirements for asset release.
During
- Enter the decedent’s information exactly as shown on official documents.
- Clearly state your role as executor or administrator.
- List each financial institution and account number accurately.
- Double-check spelling of all names.
- Review asset descriptions for clarity and completeness.
- Confirm that all required attachments are included.
- Read the affidavit statement carefully before signing.
- Sign and date the form in the correct place.
After
- Make copies of the signed affidavit and all attachments.
- Submit the form using the approved delivery method.
- Record the date you sent or filed the document.
- Monitor for confirmation or correspondence from the tax authority.
- Respond promptly to any requests for additional information.
- Provide issued waivers to financial institutions.
- Keep copies of waivers in the estate file.
- Update your internal estate accounting records.
Common mistakes to avoid with L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
- Mistake: Listing the wrong account number because you relied on memory instead of a statement, which can cause the waiver to apply to the wrong asset or be rejected, so do not forget to verify every number against an official document.
- Mistake: Signing without proper authority because you assumed family status was enough, which can invalidate the submission and delay processing, so do not forget to confirm your court appointment first.
- Mistake: Misspelling the decedent’s name due to copying from informal records, which creates mismatches with official databases and slows approval, so do not forget to match the death certificate exactly.
- Mistake: Forgetting required attachments because you thought the agency already had them, which can pause review and trigger follow-up requests, so do not forget to include clear copies upfront.
- Mistake: Leaving asset descriptions vague because you believed general wording was acceptable, which may result in limited or denied waivers, so do not forget to specify institutions and account details.
- Mistake: Assuming the preliminary waiver resolves all tax matters, which can lead to missed filing obligations later, so do not forget to track remaining tax requirements.
- Mistake: Failing to keep copies because you expected electronic records to suffice, which creates problems if documents are lost or questioned, so do not forget to maintain a complete estate file.
What to do after filling out L-4 – Affidavit Requesting Preliminary Waivers – Resident Decedents
Once you complete the affidavit, slow down and review everything one more time. Check names, dates, and account numbers against official documents. Confirm that every attachment is included and readable.
- Step 1: Make at least two full copies of the signed affidavit and all attachments.
- Step 2: Organize the original and copies in a logical order, with the affidavit on top.
- Step 3: Submit the original using the accepted filing method.
- Step 4: Note the date of submission in your estate records.
- Step 5: Track expected processing timelines so you know when to follow up.
- Step 6: Watch for written confirmation, approval, or requests for more information.
- Step 7: Provide issued preliminary waivers to each listed financial institution.
- Step 8: Confirm with each institution that the waiver satisfies its release requirements.
- Step 9: Document when funds are released or accounts are closed.
- Step 10: Update your estate accounting ledger to reflect each transaction.
Keep all correspondence in one dedicated estate file. Store copies of waivers with bank statements and transaction confirmations. If additional tax forms or filings are required later, mark those deadlines clearly. Staying organized now prevents confusion later.
Finally, communicate with beneficiaries about what the waiver does and does not accomplish. Explain that it allows certain assets to move but does not necessarily close the estate. Clear communication reduces misunderstandings and keeps the administration process on track.
Disclaimer: This guide is provided for informational purposes only and is not intended as legal advice. You should consult a legal professional.