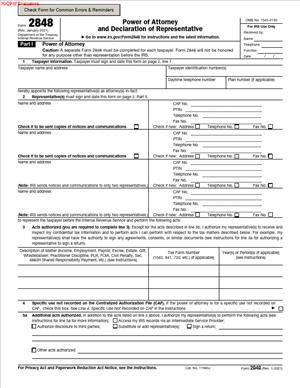
Form 2848 – Power of Attorney and Declaration of Representative
Fill out nowJurisdiction: Country: United States | Province or State: Federal
Form 2848 – Power of Attorney and Declaration of Representative is a federal tax document that lets you authorize someone to represent you before the Internal Revenue Service. It allows that person to communicate with the IRS, receive information, and act on your behalf for specific tax matters.
If you are dealing with an audit, tax debt, penalty issue, or other IRS concern, you may not want to handle it alone. This form gives another qualified individual the authority to step in and represent you directly with the agency.
The document is not a general power of attorney. It is limited to the federal tax matters you list in the form. It does not automatically apply to state taxes or other financial decisions.
Understanding how this form works helps you avoid delays, rejected submissions, and confusion about what your representative can and cannot do.
What is Form 2848 – Power of Attorney and Declaration of Representative?
Clear definition
Form 2848 – Power of Attorney and Declaration of Representative is a written authorization that allows a designated individual to represent you before the IRS. It creates a formal relationship between you and your chosen representative for specific tax matters.
The form identifies you, the representative, and the exact tax issues involved. It also defines the tax years or periods covered. Without this detail, the IRS cannot process the authorization correctly.
When accepted, the IRS communicates directly with your representative about the matters listed. Your representative can request records, respond to notices, and negotiate with the agency within the authority you grant.
Who typically uses this form?
Individuals often use this form when they are facing audits, examinations, collection actions, or disputes over federal taxes. It is common for taxpayers to feel overwhelmed by IRS procedures or technical tax rules.
Business owners also use it. A corporation, partnership, or limited liability company may appoint someone to handle payroll tax issues, income tax audits, or other federal tax matters.
Estates and trusts sometimes rely on this document when a fiduciary wants a tax professional to communicate with the IRS.
Representatives are usually attorneys, certified public accountants, enrolled agents, or other individuals authorized to practice before the IRS. The form requires them to declare their eligibility to represent you.
Why might you need this form?
You may need this form if you want someone else to speak to the IRS on your behalf. The IRS generally will not discuss your confidential tax information with another person unless proper authorization is on file.
If you receive a notice requesting documentation, a representative can gather records and respond directly. This can reduce stress and help ensure deadlines are addressed.
When negotiating payment plans or settlements, a representative can present financial information and communicate with IRS officers. The form allows those discussions to happen without you being present for every contact.
You might also use the form if you are unavailable due to travel, illness, or other obligations. It allows another qualified person to manage communications while you remain legally responsible for your tax matters.
Typical real-life scenarios
- You receive a letter stating that your individual tax return is under audit. Instead of handling interviews and document requests yourself, you authorize a tax professional to represent you for that specific tax year.
- Your small business owes payroll taxes. An IRS revenue officer contacts you about collections. You complete the form to allow a representative to discuss payment options and submit the required financial statements.
- You disagree with a penalty assessed for late filing. A representative prepares a written explanation and communicates with the IRS appeals function under the authority granted in the document.
- You are the executor of an estate and need assistance resolving final income tax filings. You authorize a qualified individual to represent the estate for the listed tax periods.
- You operate multiple businesses and want one central representative to handle specific income tax issues for defined years. The form lets you limit the authorization to only those matters.
When would you use Form 2848 – Power of Attorney and Declaration of Representative?
You use this form when the IRS requires formal authorization before discussing your tax information with another person. Verbal permission over the phone is usually not enough for ongoing representation.
It is commonly used during audits, examinations, and appeals. In these situations, communication with the IRS may involve technical discussions, document submissions, and formal responses. A designated representative can manage that process.
Collection matters are another frequent reason. If the IRS is seeking payment for back taxes, your representative may communicate about installment agreements or other collection alternatives, depending on the authority granted.
Businesses often use the form when delegating tax compliance issues to internal staff or outside professionals. The authorization can be limited to certain tax types, such as employment taxes, or certain periods.
You might also use it when you want someone to receive copies of IRS notices for oversight purposes. The form allows you to specify whether your representative can receive and inspect confidential tax information.
The key point is that the form is tied to the federal tax administration. It is not used for general financial decisions, banking matters, or state-level tax agencies.
Legal characteristics of Form 2848 – Power of Attorney and Declaration of Representative
This document becomes effective when it is properly completed, signed, and accepted by the IRS. It must clearly identify the taxpayer, the representative, and the tax matters involved.
The form requires specific details about the type of tax, the form number related to that tax, and the years or periods covered. Vague entries can lead to delays or rejection.
Both you and the representative must sign the document. The representative must also declare their professional designation and confirm they are authorized to practice before the IRS.
Common issues that cause problems include missing signatures, incorrect tax periods, incomplete representative information, or listing unauthorized individuals. Errors can prevent the IRS from recognizing the authorization.
This is a federal form. While many states have similar documents for state tax matters, this filing applies only to federal tax issues handled by the IRS.
The form does not transfer your tax liability to the representative. You remain responsible for filing accurate returns and paying any taxes owed. The representative acts on your behalf but does not assume your legal obligations.
It also does not automatically revoke all prior authorizations unless you indicate that intent. If you previously filed a similar authorization, you may need to address whether it remains in effect.
Is it legally binding?
Yes, it is legally binding once properly executed and accepted by the IRS. By signing, you are formally granting the listed representative authority to act within the scope described in the document.
The binding effect applies only to the specific tax matters and periods you identify. If a tax year or type of tax is not listed, the representative generally has no authority for that matter.
The representative is bound by professional and ethical rules that govern practice before the IRS. Their authority is limited by both the form and the governing standards.
If the form is incomplete, unsigned, or rejected by the IRS, it will not be effective. Accuracy and proper completion are essential for the authorization to function as intended.
How to fill out Form 2848 – Power of Attorney and Declaration of Representative
Step 1 – Identify the taxpayer
Enter your full legal name exactly as it appears on your most recent tax return. Provide your mailing address and taxpayer identification number, such as a Social Security number or employer identification number. If the matter involves a business or estate, use the correct legal name and identification number for that entity.
If a joint return is involved, each spouse typically must complete and sign a separate form unless specific instructions allow otherwise. Make sure the identifying information matches IRS records to avoid processing delays.
Step 2 – Appoint your representative
List the full name and contact information of each representative you want to authorize. Include their address, phone number, and any required identification details.
You may name more than one representative. The form allows you to indicate whether each representative can act independently or whether certain actions require joint participation. Clear entries prevent confusion about who has authority.
Step 3 – Describe the tax matters and periods
Specify the type of tax involved, such as income, employment, or excise tax. Enter the related form number and the exact tax years or periods covered.
Be precise. For example, list individual years or clearly defined ranges. Do not leave this section general or open-ended. The IRS relies on this section to determine the scope of authority.
If you want the authorization to apply to future periods, follow the instructions in the form carefully when describing them.
Step 4 – Grant or limit specific acts
Review the section that outlines what your representative can do. The form describes standard powers, such as receiving confidential information and representing you in conferences with the IRS.
If you want to restrict certain actions, indicate those limitations clearly in the space provided. If you want to allow specific additional acts that are permitted by the form’s instructions, describe them accurately.
Read this section closely. It defines the practical authority your representative will have once the document is processed.
Step 5 – Address prior authorizations
Indicate whether this filing revokes earlier powers of attorney on file with the IRS for the same matters and periods. The form provides a way to clarify your intent.
If you want to keep an earlier authorization in effect, follow the instructions for attaching copies or providing required details. Clear communication in this section avoids unintended cancellation.
Step 6 – Sign and date the form
Sign your name in the taxpayer signature section and enter the date. If you are signing in a representative capacity, such as an officer of a corporation or executor of an estate, include your title.
Your signature confirms that you are granting the authority as described. An unsigned form is not valid and will not be processed.
Step 7 – Representative declaration and signature
Each representative must complete the declaration section. They must indicate their professional designation and confirm that they are authorized to represent you before the IRS.
The representative must sign and date this section. Without their signature, the authorization is incomplete. Once both sides have signed, the form is ready for submission according to the applicable IRS procedures.
Legal terms you might encounter in Form 2848 – Power of Attorney and Declaration of Representative
- Taxpayer Identification Number (TIN): This is your Social Security Number, Employer Identification Number, or Individual Taxpayer Identification Number. In this document, the TIN connects the authorization to the correct taxpayer account. If the number does not match the tax account on file, the authorization may not post.
- Representative: The individual you appoint to act on your behalf before the Internal Revenue Service. This person must be eligible to practice before the agency, such as an attorney, certified public accountant, or enrolled agent. The form records their name, address, contact details, and identifying number.
- CAF Number: The Centralized Authorization File number assigned to representatives who regularly practice before the agency. If your representative already has one, you enter it so the authorization links to their existing profile. If they do not have one, the agency will issue it after processing.
- Tax Matters: The specific issues you are authorizing your representative to handle. You must list the type of tax, the form number, and the years or periods involved. The authority only applies to what you clearly describe here.
- Tax Periods: The calendar years, fiscal years, or specific periods covered by the authorization. This section limits the scope of the representative’s power. If you leave out a year, your representative cannot act for that year.
- Specific Acts Authorization: A section where you grant or restrict particular powers, such as signing a return or receiving refund checks. You can customize what your representative may or may not do. What you write here controls the limits of their authority.
- Revocation of Prior Power of Attorney: A statement that cancels earlier authorizations on file for the same tax matters and periods. If you check the box, prior powers of attorney for those matters are revoked automatically. If you do not, earlier authorizations may remain active.
- Declaration of Representative: The portion your representative signs to confirm their eligibility and professional status. They must indicate the category under which they are authorized to practice. Without this signed declaration, the document is incomplete.
- Retention or Withdrawal: The concept that an authorization stays in effect until it is revoked or withdrawn. You can revoke it by filing a new authorization or a written revocation. The representative can also withdraw by notifying the agency in writing.
FAQs
Does this document allow my representative to receive my tax refund?
Not automatically. You must review the section that discusses specific acts and confirm whether you are granting authority to receive or endorse refund checks. If you do not clearly grant that authority, your representative can discuss your account but cannot receive funds on your behalf.
What tax years should I list on Form 2848 – Power of Attorney and Declaration of Representative?
You should list each tax year or period you want covered, such as 2022, 2023, or a specific quarterly period. Check your notices or transcripts to confirm the exact periods at issue. If a year is missing, your representative will not have authority for that year.
Can I name more than one representative?
Yes. You can list multiple representatives in the designated section. Make sure you provide complete contact details and identification numbers for each person so the authorization can be processed without delay.
What happens if my representative does not sign the declaration section?
The authorization will not be valid until the representative signs and dates the declaration. The agency will not recognize the authority if that section is incomplete. Always confirm that both you and your representative have signed in the correct places.
Does this form replace an earlier power of attorney I filed?
It can. There is a section where you indicate whether you want to revoke prior authorizations for the same matters and periods. If you check the revocation box, earlier powers of attorney for those items are cancelled; if you leave it unchecked, they may remain active.
Can my representative sign my tax return using this document?
Generally, signing a return requires specific authority and may depend on your situation. You must look at the section on specific acts and confirm whether signing returns is allowed. If you do not grant that authority clearly, your representative cannot sign for you.
How do I know if the agency accepted this form?
After submission, you can confirm acceptance by contacting the agency directly or by checking whether your representative can access your account information. If the authorization has been posted, the representative will be able to discuss the listed tax matters. Keep a copy of the signed document in case you need to verify details.
Can I cancel Form 2848 – Power of Attorney and Declaration of Representative later?
Yes. You can revoke it at any time by submitting a written revocation or filing a new authorization that replaces it. Make sure you clearly identify the tax matters and periods you are cancelling so there is no confusion about what remains in effect.
Checklist: Before, During, and After Form 2848 – Power of Attorney and Declaration of Representative
Before
- Confirm the exact tax matters and years you want covered.
- Verify your legal name and Taxpayer Identification Number as shown on your most recent tax return.
- Confirm your representative is eligible to practice before the agency.
- Collect your representative’s address, phone number, and identification number.
- Decide whether you want to revoke prior authorizations.
- Review any notices or letters related to the tax issues.
- Discuss with your representative what powers you are comfortable granting.
During
- Print or type your name and TIN exactly as they appear on your tax records.
- List each tax form number and each tax period clearly.
- Double-check the spelling of your representative’s name.
- Enter the representative’s CAF number if available.
- Review the specific acts section and adjust as needed.
- Check or leave unchecked the revocation box intentionally.
- Sign and date the form in the correct section.
- Ensure your representative completes and signs the declaration.
After
- Make a complete copy of the signed document for your records.
- Provide a copy to your representative.
- Submit the form using the appropriate submission method.
- Confirm receipt or processing after a reasonable time.
- Monitor correspondence to see if your representative is copied.
- Keep notes of the date you submitted the authorization.
- Update your records if you later change representatives.
- Store the document with your tax files for the covered years.
Common mistakes to avoid with Form 2848 – Power of Attorney and Declaration of Representative
- Mistake: Listing general descriptions like “all taxes” without specifying form numbers and periods, which happens when you rush through the tax matters section, leading to rejected or limited authority. Do not forget to identify each tax type and year clearly.
- Mistake: Entering an incorrect TIN or misspelling your name because you rely on memory, which can prevent the authorization from posting to your account, so do not forget to copy the information exactly from a recent return.
- Mistake: Forgetting the representative’s signature in the declaration section, often because you assume your signature is enough, which results in an incomplete filing, so do not forget to confirm that both parties signed.
- Mistake: Failing to check the revocation box when you intend to replace a prior authorization, which happens when you overlook that small section, causing multiple representatives to remain authorized. Do not forget to review prior powers of attorney.
- Mistake: Granting broader powers than intended because you do not read the specific acts’ language carefully, which can allow actions you did not anticipate, so do not forget to limit authority in writing if needed.
- Mistake: Submitting the form but not confirming acceptance, which happens when you assume processing is automatic, potentially delaying your representative’s ability to act, so do not forget to follow up and verify it has been posted.
What to do after filling out Form 2848 – Power of Attorney and Declaration of Representative
Once you complete and sign the form, your next focus is proper submission and confirmation. The document does not take effect simply because you filled it out. It must be received and processed.
- Step 1: Make at least one clear copy of the fully signed form for your records.
- Step 2: Provide a copy to each appointed representative.
- Step 3: Review the submission instructions to determine the correct method of filing.
- Step 4: Submit the form using the designated channel for the tax matter involved.
- Step 5: Note the date and method of submission in your records.
- Step 6: Allow time for processing and then confirm that the authorization has been recorded.
- Step 7: Ask your representative to verify that they can access your account information.
- Step 8: Watch for future correspondence to ensure copies are sent to your representative.
- Step 9: Store the signed original with your tax documents for the listed years.
- Step 10: If circumstances change, prepare and file a revocation or updated authorization promptly.
Staying organized after submission protects you. Keep all related notices, letters, and confirmations together. If you later expand the scope to new tax years or issues, you may need to submit a new authorization that clearly lists those additional matters.
Finally, review your overall records. Update any internal files to reflect who is authorized to speak on your behalf and for which years. Clear documentation prevents confusion and ensures your representative can act efficiently when needed.
Disclaimer: This guide is provided for informational purposes only and is not intended as legal advice. You should consult a legal professional.